Your Local Broker with access to multiple banks & loan programs
Located in Reseda, CA
Certified Divorce Lending Professional
Hovig Khatchadourian is a Certified Divorce Lending Professional (CDLP®). Divorce brings mortgage questions most loan officers aren't trained to answer, and getting them wrong can cost you the house.
Hovig works alongside you, your attorney and your financial professionals before the settlement is final, so the plan for the home actually works when it's time to qualify.
- Keeping the home and buying out your spouse's equity
- Qualifying on your own income, including support income
- Refinancing to remove an ex-spouse from the loan
- Buying your next home after the divorce
Personalized Mortgage Experience
Hovig Khatchadourian offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Reseda, CA .
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
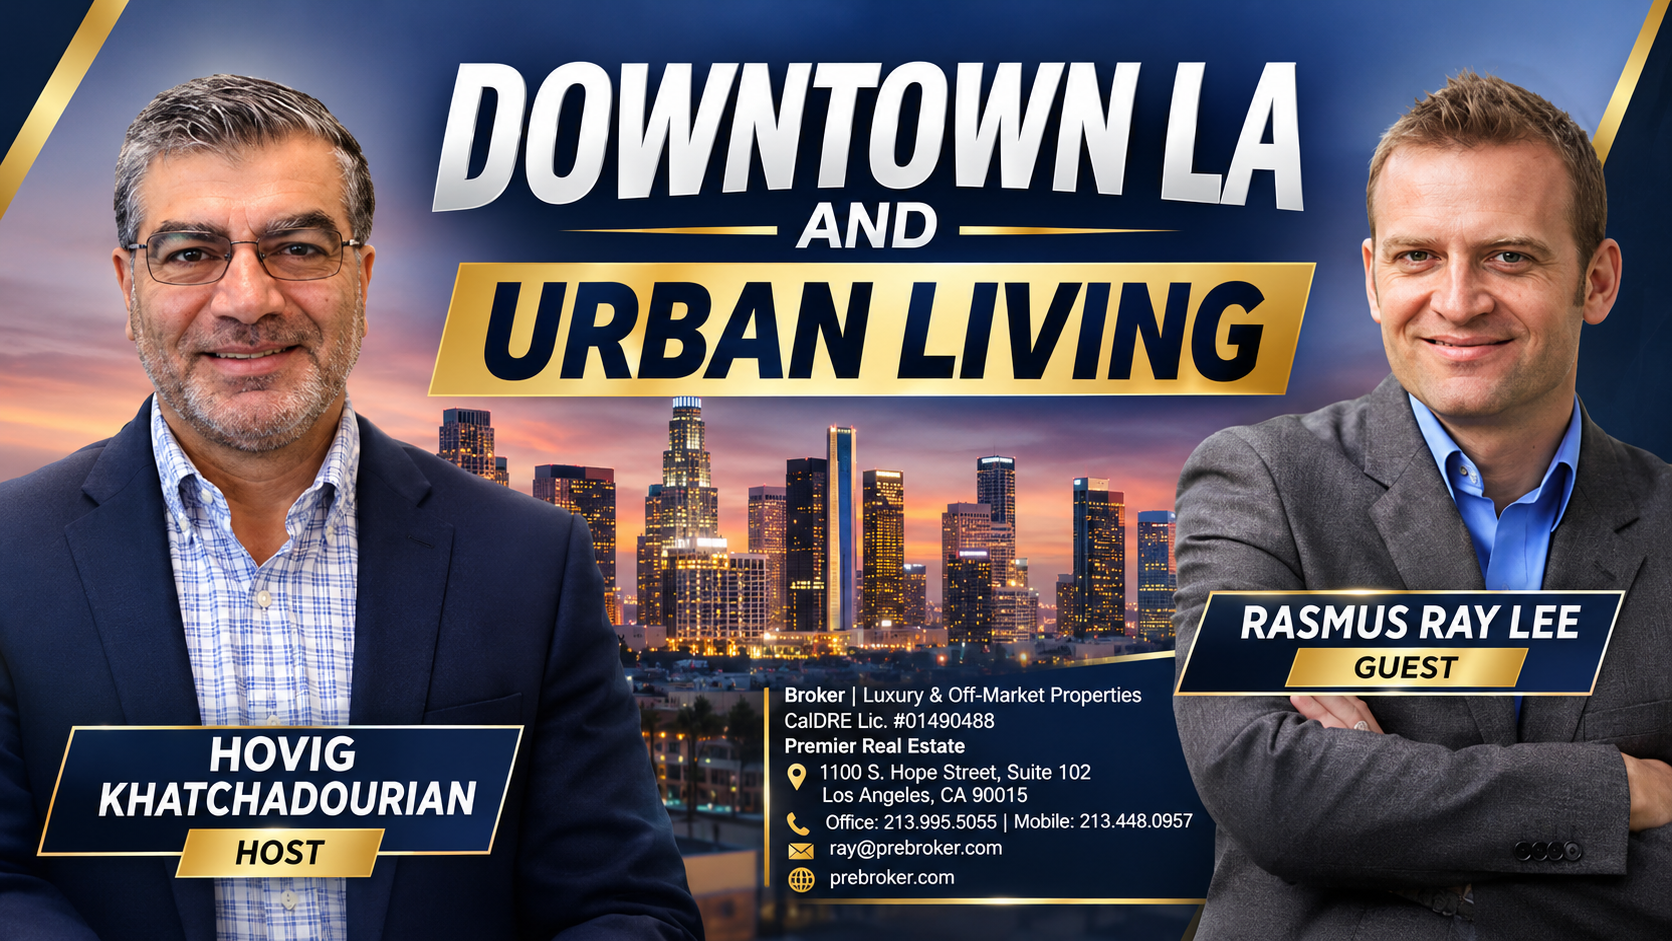
Downtown LA Realtor Ray Lee on Lofts, Urban Living, and Buying Now
Mortgage and Money With Hovig
On his show, Hovig Khatchadourian brings valuable conversations with local experts who understand the real estate markets they serve. This episode focused on downtown Los Angeles and urban living, with guest Rasmus Ray Lee of Premier Real Estate. Ray has been involved in downtown LA real estate for more than 20 years and specializes in the residential market, especially lofts and urban living. Hovig wanted to learn how the market has evolved and where it is headed.
From Jazz Saxophonist to Downtown Specialist
Ray is originally from Copenhagen, Denmark, and came to the United States in the early 1990s to play music. He spent about ten years in New York as a professional jazz saxophonist, touring, recording, and performing with his own trio at the Guggenheim Museum, before moving to Los Angeles in 1997. After some odd jobs, he entered real estate in 2004 as an assistant to his business partner, who was one of the first people to buy downtown as an investment, and the two started their company together. Ray earned his license in early 2005. He believed that if Los Angeles built high rises and revitalized a downtown that had been ignored for decades, it could become something like a small Manhattan, and the warm climate could only help. The company stayed busy through the credit crisis by handling short sales and foreclosures for both buyers and sellers.
How Downtown Has Changed
When Ray started, many developer contracts were waiting to be fulfilled, interest rates were low, and the market was hot, with some units in South Park buildings like Flower Street Lofts selling several times in the first year. Early buildings were mostly warehouse conversions, such as Flower Street Lofts and Grand Lofts in South Park and several loft buildings in the Arts District. Since then, most additions have been new towers, along with conversions of older apartment and office buildings in the historic core, financial district, and fashion district. Bunker Hill has long been the Beverly Hills of downtown, with towers dating back to the 1960s. Ray says that in his area, South Park, also called the Social District, nearly every parking lot has been purchased by developers who are waiting on entitlements.
What’s Coming Next
Ray says some units converted from apartments to condos are still being sold, including in the Metropolis towers. Oceanwide Plaza, stalled since 2019, is finally being built again, with plans for a hotel and condos plus a mall at the bottom, and it has reportedly been taken over by a different developer. Several other lots nearby are owned by developers but have not started, because construction loans are too expensive at current rates. He expects at least four or five projects within ten years, including a possible W Hotel project across from LA Live. Development timelines can change with financing, permits, and economic conditions.
Who Is Buying Downtown
Ray is currently in escrow on two properties, representing the sellers, and both buyers plan to live in them. He sees buyers of all ages and cultures, including parents buying for children at USC, as well as doctors, nurses, and professors. He has noticed an uptick in owner-occupied purchases, especially in his area, and enjoys the mix of lifestyles.
What Buyers Should Ask
Ray says future value varies by building, price per square foot, view, and floor, so buyers should ask their agent what likely future value looks like. They should also look closely at the HOA, including what dues cover and how the association is performing. In his experience, downtown HOAs are relatively well maintained, though dues have risen in some buildings because of costs outside their control, such as city services, utilities, and higher wages for building staff. HOA dues, rules, and finances vary by building, so review the documents for any property you consider.
Neighborhoods and Lifestyle
Downtown has several districts that feel like distinct neighborhoods, each with its own culture. South Park, or the Social District, is where Ray lives. The fashion district is home to wholesale boutiques. The Arts District sits near the Boyle Heights bridges, and the financial district, Bunker Hill, the historic core, and the central district behind LA Live round out the list. Ray praises the restaurants, including the authentic Japanese food in Little Tokyo and a Taiwanese restaurant a block from him called Pine and Crane. There is also a Saturday farmers market in his neighborhood, with live music, on Grand between Olympic and 11th. Buildings range from historic structures dating to the Charlie Chaplin era and converted World War II era warehouses to new towers. Most buildings include at least one parking space with a one-bedroom and often two for larger units.
The Buyer’s Market and the Olympics
Ray agrees with Hovig that it is a buyer’s market. High interest rates have pushed prices down, price reductions have been happening for two to three years, and sellers are often willing to come down a little more. Ray believes the bottom is here or near and recommends buying now or soon. He also points to the 2028 Olympics as a positive influence, noting repaved streets, more proactive policing, and a reduction in homelessness, and says he is starting to feel the vibe downtown had in 2019. Business improvement districts, funded by property owners, also provide safety patrols and street cleaning. Ray’s views on prices and the market are his own opinions, and conditions vary by building and neighborhood.
Hovig’s Take on Rates
Ray asked Hovig where rates are headed. Hovig, who studies bond charts, said he believes October 1, 2026 marked a turning point, with the bond market double-bottoming against the 2007 low. If that low holds, he expects mortgage rates to trend lower over the next one to three years, with rates likely staying in the 6% to 7% range for the next six months or so amid political uncertainty, and then potentially moving toward 5%, though 4% would be a stretch. Hovig stressed that rates move slowly and that this is only his projection and could be wrong. Because of that, he suggests focusing on the opportunity to get a good deal now and treating a future refinance as a possibility rather than a certainty.
Connect With Ray Lee
Rasmus Ray Lee of Premier Real Estate can be reached at 213-448-0957 or by email at [email protected]. Hovig plans to include contact details with the episode.
Sources
NAR.realtor
ConsumerFinancialProtectionBureau.gov
FreddieMac.com
Fanniemae.com
HUD.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Contact Us
(818) 307-5544
21300 Victory Blvd
3rd floor, Suite 76
Woodland Hills,
CA 91367
